Tax deductibility

Our platform complies with tax guidelines, allowing you to deduct expenses related to attending our lecture series.

  • Course / lecture fees
  • Qualifying business travel
  • Reasonable accommodation
  • Eligible meals

Validated by Deloitte

Validated seal

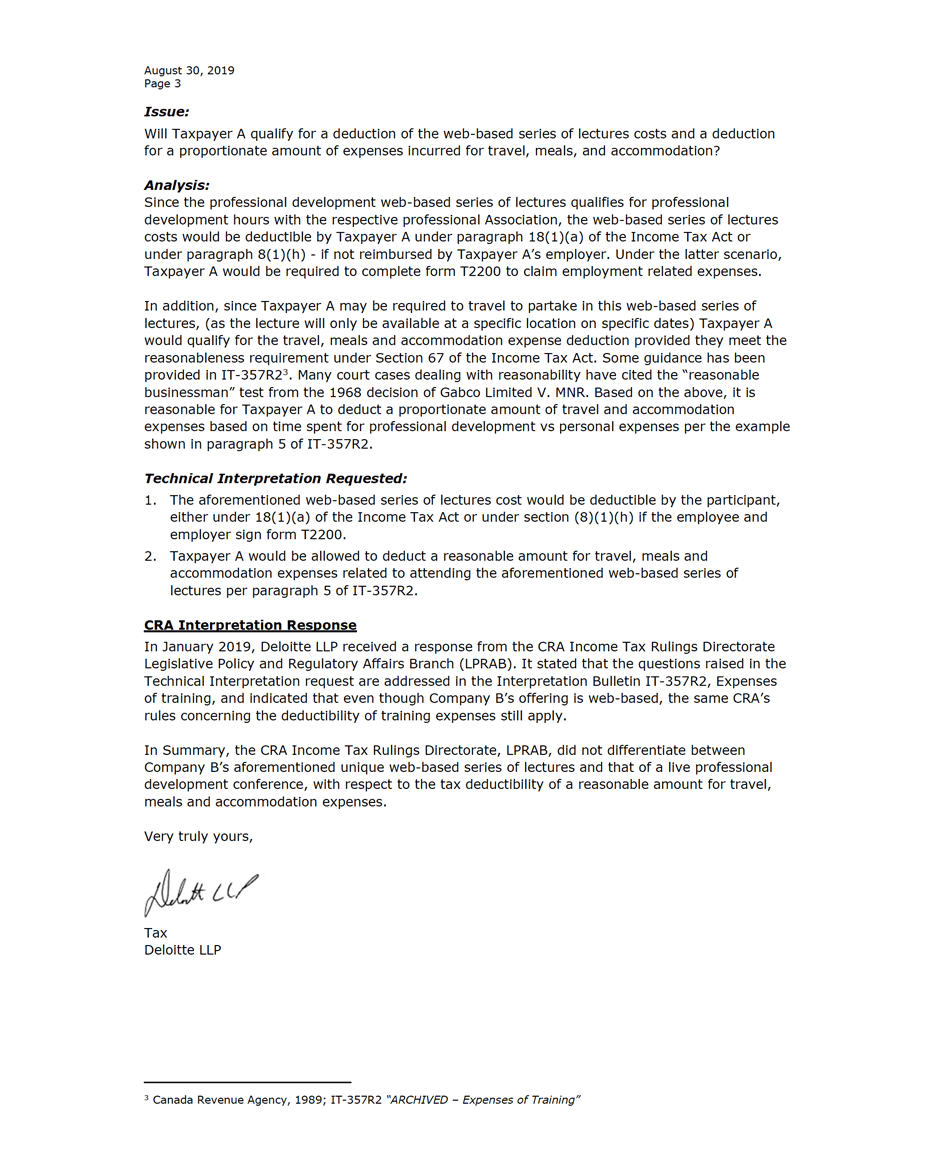
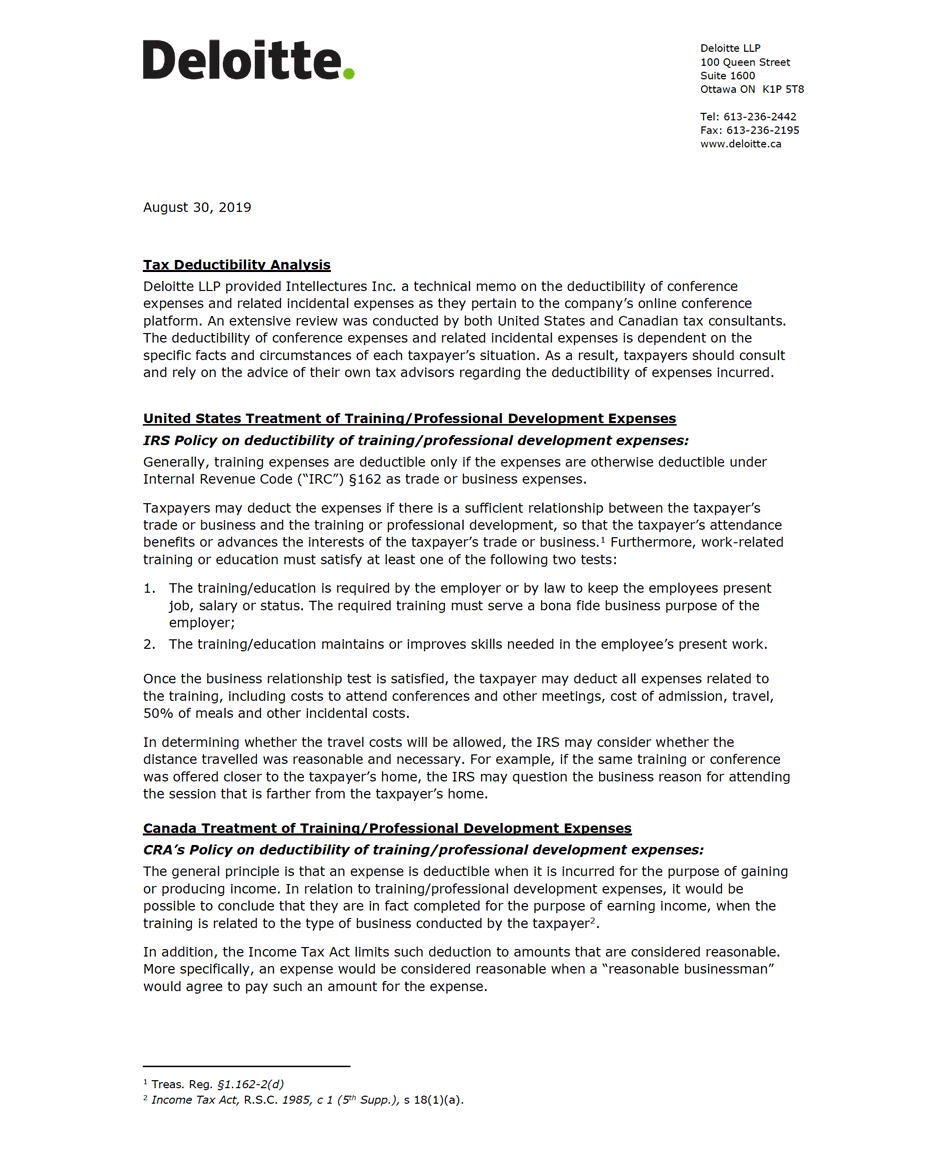
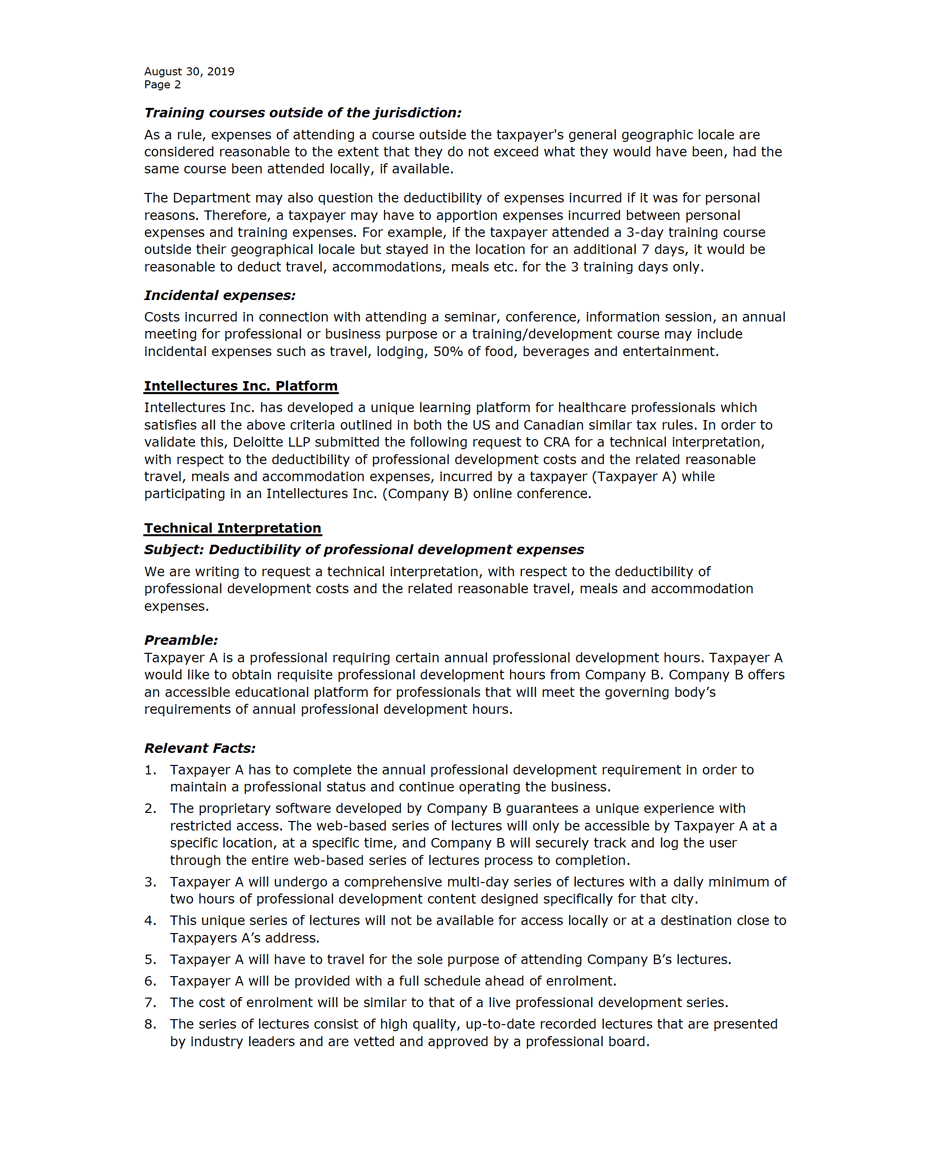
Deloitte LLP's August 30, 2019 letter summarizes a Canadian and U.S. tax analysis and reports a January 2019 CRA response. According to Deloitte, CRA said its existing training-expense guidance also applies to the specific web-based lecture series described in the request.

2026 Regulatory Review Update

Intellectures' 2026 review reports that there have been no changes to the relevant Canadian or U.S. tax laws, regulations, or administrative guidance used in assessing the tax-deductibility eligibility of the Intellectures platform.

How the rules apply

Canadian tax rules

Canada

Under Canada Revenue Agency (CRA) guidance, reasonable training expenses may qualify for tax deductions when education maintains, updates, or upgrades existing skills within a business or profession. Eligible expenses may include training course fees and associated costs for travel, transportation, food, beverages, and lodging incurred in connection with attending a qualifying training course, subject to applicable tax rules.

Training Courses vs. Conventions

The CRA distinguishes training courses from conventions and business meetings, which may receive different tax treatment. Under subsection 20(10) of the Income Tax Act, deductions for qualifying convention expenses are generally limited to two conventions per year.

In contrast, there is no equivalent annual numerical limit on deductions for qualifying training courses. Individuals carrying on a business or profession may deduct eligible expenses associated with multiple training courses throughout the year, provided each course and its related expenses satisfy the applicable CRA requirements.
U.S. federal tax rules

United States

Under Internal Revenue Service (IRS) guidelines, Continuing Medical Education (CME), professional conferences, seminars, and training courses may qualify as tax-deductible business expenses when they maintain or improve skills required in an existing profession or fulfill employer or legal requirements to maintain professional status, licensure, or employment. Qualifying education must not be undertaken to meet minimum entry requirements or qualify for a new trade or business.

Deductible Training and Travel Expenses

For eligible taxpayers, including self-employed physicians, deductible expenses may include CME registration fees, educational materials, transportation, airfare, lodging, and meals incurred in connection with attending qualifying educational activities. The IRS specifically recognizes medical refresher courses as qualifying work-related education. Associated travel expenses may also be deductible when travel is primarily undertaken for qualifying educational or business purposes, subject to applicable IRS regulations.

No Annual Limit on Qualifying CME Activities

The IRS does not impose a general annual numerical limit on the number of qualifying CME courses, medical conferences, seminars, or professional training activities that may be deducted. Eligible professionals may deduct qualifying expenses associated with multiple educational activities throughout the year, provided each activity meets the applicable IRS requirements.

Employer-Paid CME

Employed physicians may also benefit from tax-advantaged CME through employer-sponsored professional development programs.

Under IRS guidelines, employers may directly pay or reimburse qualifying work-related CME expenses, including educational fees and eligible travel, lodging, and meals, through compliant reimbursement arrangements. These benefits may be excluded from the employee's taxable income when applicable requirements are satisfied.

Qualifying work-related educational benefits are not subject to a general annual numerical limit on the number of CME activities attended.

International tax rules

International

Many countries outside Canada and the United States have tax provisions that may allow professionals to deduct expenses associated with continuing professional education, training courses, medical conferences, and other work-related educational activities.

Depending on the country and applicable tax regulations, eligible expenses may include registration fees, educational materials, travel, transportation, meals, and lodging incurred in connection with qualifying professional development activities.

Tax deductibility requirements vary by country and individual circumstances. Professionals are encouraged to consult a qualified tax advisor or accountant in their country of tax residence to determine the eligibility of their educational expenses and any applicable restrictions or limitations.

Your participation records

Deloitte's 2019 CRA submission described a location-restricted, multi-day program and secure participation tracking. Throughout the entire web-based lecture series, Intellectures securely tracks, records, and maintains detailed participation logs, providing documented evidence of engagement and completion of the educational activities. These records may assist participants in substantiating their professional development activities and supporting applicable tax-deductibility claims, subject to relevant tax regulations.

Ready to get started?